Insurance India

Dear viewers, here you can get the proper information of insurance and financial investment

Breaking

Showing posts with label PENSION PLANS. Show all posts

Monday, October 22, 2018

8:15 AM

Pradhan Mantri Vaya Vandana Yojana (842)

Pradhan Mantri Vaya Vandana Yojana (Plan No: 842) 


This is a pension plan for senior citizens who are 60 years and above. Under this scheme, senior citizens will get a guaranteed return of 8% for 10 years. This plan is exempted from Goods and services tax (GST). The scheme will be available for one year from date of launch. LIC has already sold 58,152 policies so far and collected Rs. 2,705 crore since its soft launch on 4th May 2017. This policy can be purchased online as well as offline. 

The plan UIN is 512G311V01.

  1. The investment limit has been increased to 15 lakhs under the Pradhan Mantri Vaya Vandana Yojana (PMVVY). The earlier limit was 7.5 lakhs.
  2. The last date to apply for Pradhan Mantri Vaya Vandana Yojana (PMVVY) has been extended to 31st March 2020. It was earlier supposed to end on 4th May 2018
  3. The limit on maximum investment has now revised to per senior citizen(and not per family). So now in a family, if both husband and wife are senior citizens. Both can invest 15 lakhs each as purchase price (total 30 lakhs) and can enjoy bonus facility.

Plan Parameters:

Age at Entry60 Years (Completed) 
Calculate your Age
Maximum Age at EntryNo Limit
Policy Term10 Years (Fixed)
Pension Receiving ModeMonthly, Quarterly, Half Yearly or Yearly


Eligibility conditions in Pradhan Mantri Vaya Vandana Yojana?


 MinimumMaximum
Age60 Years (Completed)No Limit
Policy Term10 Years
Pension ModeMonthly, Quarterly, Half-yearly or Yearly
Purchase PriceRs. 1,50,000 for monthly
Rs. 1,49,068 for quarterly
Rs. 1,47,601 for half-yearly
Rs.1,44,578 for yearly
Rs. 15,00,000 for monthly
Rs. 14,90,683 for quarterly
Rs. 14,76,015 for half-yearly
Rs. 14,45,783 for yearly
Pension AmountRs. 1,000/- per month
Rs. 3,000/- per quarter
Rs.6,000/- per half-year
Rs.12,000/- per year
Rs. 10,000/- per month
Rs. 30,000/- per quarter
Rs. 60,000/- per half-year
Rs. 1,20,000/- per year
 
The maximum pension amount criteria in this plans are for per senior citizen. 

Mode of pension payment: 

The modes of pension payment are monthly, quarterly, half-yearly & yearly. The pension payment shall be through NEFT or Aadhaar Enabled Payment System.

Pradhan Mantri Vaya Vandana Yojna Benefits:

  • Pension Payments
On survival of the policyholder during the policy term of 10 years, the pension is payable at the end of each period as per the mode of monthly/ quarterly/ half yearly/ yearly as chosen by the pensioner at the time of purchase. 
For every Rs. 1,000 invested in the plan, 
  1. Rs. 80 will pay out in the monthly mode
  2. Rs. 80.5 paid out in the quarterly mode
  3. Rs. 81.3 will paid out in the half-yearly mode
  4. Rs. 83 paid out in the yearly mode

Use this Calculator to calculate the Annuity in Pradhan Mantri Vaya Vandana Yojana.

  • Death Benefit
On the death of the policyholder during the policy term of 10 years, the Purchase Price shall be refunded to the beneficiary.
 
  • Maturity Benefit
On survival of the policyholder to the end of the policy term of 10 years, Purchase price along with final pension installment shall be returned.
 
  • Surrender Value
The policy allows premature exit during the policy term under exceptional circumstances like the Pensioner requiring money for the treatment of any critical/terminal illness of self or spouse. The Surrender Value payable in such cases shall be 98% of Purchase Price.
 
  • Loan
Loan facility is available after completion of 3 policy years. The maximum loan that can be granted shall be 75% of the Purchase Price
For the financial Year 2016-17, the applicable interest rate to be charged is 10% p.a.
 
  • Free Look period
If a policyholder is not satisfied with the “Terms and Conditions” of the policy, he/she may return the policy to the Corporation within 15 days (30 days if this policy is purchased online) from the date of receipt of the policy stating the reason of objections.
In this case, the policyholder will get the entire amount after deducting the charges for Stamp duty and pension paid (if any).
 
  • Exclusions
Suicide - There shall be no exclusion on the count of suicide and full Purchase Price shall be payable.
 
  • Tax Benefit
The deposits made in the scheme are exempt from income tax under section 80C of Income Tax Act, 1961. However, the interest earned on the deposit is not exempt from income tax. Provisions of Tax Deduction at Source (TDS) are applicable to the Scheme.

Pradhan Mantri Vaya Vandana Yojna Example:

Let us understand this plan with the help of an example.
Suppose Ramesh with following details has taken this plan. He invests a lump sum from his savings to ensure a fixed regular income for the next 10 years.

Age: 60 years
Purchase Price: Rs. 7,50,000
Policy Term: 10 years
Purchase Year: 2017
Pension Mode: Monthly
 
So the benefits received by Ramesh in the Pradhan Mantri Vaya Vandana Yojna will be as follows:

Pension Benefit 
Ramesh will receive Rs. 5,000 as pension amount at the end of every month for 10 years. The rate of interest is 8%. So 8% of Rs. 7,50,000 divided by 12 is what he will get every month. This is of course if he survives the 10-year term.
 
Maturity Benefit
On completion of 10 years, Ramesh will receive the purchase price i.e Rs. 7,50,000 which he had paid to purchase the plan.
 
Death Benefit
In case Ramesh dies at the age of 65 - Till the age of 65, he will receive the monthly pension of Rs. 5,000 and on his death the purchase price i.e Rs. 7,50,000/- will be payable to his nominee. This is true for his death at any time during the policy term of 10 years.
 
Surrender Benefit
Suppose at the age of 68 Ramesh needs his money for treatment of some critical illness of self or spouse. In such a scenario, till the age of 68, he will receive a monthly pension of Rs. 5,000 and at the age of 68 when he surrenders the policy he will be refunded 98% of purchase price i.e. 98% of 7,50,000 = Rs. 7,35,000.


If you have any questions on this plan, please drop a comment and we would be happy to help you. 

VIDEO TUTORIAL:


Saturday, October 20, 2018

7:59 AM

Jeevan Akshay VI (189)

LIC Jeevan Akshay Plan:


LIC’s Jeevan Akshay VI (Plan No: 189) is a pension plan, which provides monthly pension throughout the life on payment of single lump sum amount. This is an immediate Pension plan that enables starting of immediately pension on the purchase of this policy. There are 10 different options which are available in which pension can be received. The maturity of Endowment plans e.g. Jeevan Anand or New Endowment plan can be used to buy this plan at maturity. A person can plan such that, at the age of 55 or 60 he buys this plan and enjoy his retirement with the regular pension for the lifetime. You may calculate pension using the Pension Calculator as per your one-time single amount and pension starts.

LIC Jeevan Akshay 6 Plan Review:

LIC Jeevan Akshay VI Policy is a Single Premium Immediate Annuity Plan
How it works – You pay a Single Premium (also called the 'Purchase Price') to purchase an Annuity. LIC will then pay you regular amounts for the rest of your life. You could receive this regular payout monthly, quarterly, half-yearly or annually. This regular payout amount is called an Annuity. You have 7 options to decide on the type and amount of annuity you want to receive.

Our take – If you have already purchased a Pension Plan (also called Deferred Annuity plan) from LIC you will have to buy an Annuity from LIC itself. As per the current regulations, at Vesting Age you can withdraw a maximum of 1/3 of the accumulated amount and the rest has to be used to purchase an Annuity from the same insurance company. So it is best to decide which of the 7 options best suits you. The details of the 7 Annuity options and the benefits are explained below.
You can of course by an Annuity by investing a lump sum which you have as savings. You will then be assured of a regular payout as long as you are alive. It works well for those who want a confirmed amount for the rest of their lives and are not necessarily looking at options which may offer them higher returns with an element of unpredictability. For example, there may be a period where Fixed Deposits offer better returns than the Annuity, but then the FD rates may go down also within a year or so.

Key Features:

  • Single premium and immediate pension.
  • Retirement Planning.
  • 10 different methods for getting the pension.
  • Option to secure the pension for the spouse.
  • Option for the guaranteed pension for a fixed period.

Plan Parameters

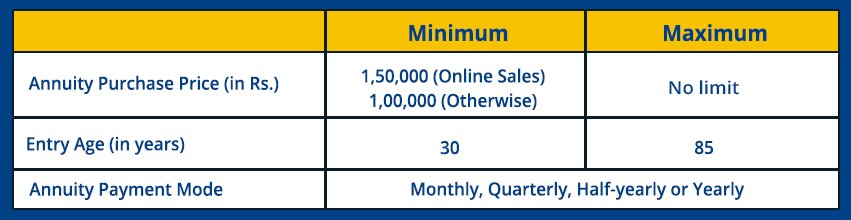
Minimum Age at entry30 Years (completed)
Maximum  Age at Entry85 years (completed)
Minimum Single Premium1,00,000 (No Maximum Limit)
Medical requirementNot required
Mode of PensionYearly, Half-yearly, Quarterly, Monthly
SurrenderNot Applicable

Pension Options:

One of the following options may be selected at the time of buying plan and the same cannot be changed in the future.
OptionHow Pension will be ReceivedWhat will happen in case of death
1Pension payable for life at a uniform rate.Pension Stops.
2Pension payable for 5 years guaranteed and thereafter as long as the Policyholder is alive.1. Death during a guaranteed period, the pension is paid to nominee till the end of the guaranteed period.

2. On death after the guaranteed period, pension stops.
3Pension payable for 10 years guaranteed and thereafter as long as the Policyholder is alive.
4Pension payable for 15 years guaranteed and thereafter as long as the Policyholder is alive.
5Pension payable for 20 years guaranteed and thereafter as long as the Policyholder is alive.
6Pension for life with return of purchase price on death of the Policyholder.Pension stops and paid amount returned to the nominee.
7Pension payable for life increasing at a simple rate of 3% p.a.Pension stops.
8Pension for life with a provision of 50% of the Pension payable to spouse during his/her lifetime on death of the Policyholder.50% of pension amount to spouse (wife or husband) for the lifetime.
9Pension for life with a provision of 100% of the Pension payable to spouse during his/her lifetime on death of the Policyholder.100% of pension amount to spouse (wife or husband) for the lifetime.
10Pension for life with a provision of 100% of the Pension payable to spouse during his/ her lifetime on death of Policyholder. The purchase price will be returned on the death of the last survivor.100% of pension amount to spouse (wife or husband) for a lifetime and on the death of the spouse (wife or husband) purchased amount is returned to the nominee.

Annuity Options in Jeevan Akshay VI Plan:

There are 7 Annuity Options in this plan.

We will explain each option with the following example:
One time payment (Purchase Price) = Rs. 5,00,000 (5 lakhs) with the pension starting in Annual mode at the age of 60 years.
 
Option 1 - Annuity for Life: where the pension is paid till the policyholder is alive. The pension received regularly is uniform and does not change.
Example: The policyholder would receive an annual pension of Rs. 48,750 for the rest of his/her lifetime.

Option 2 - Annuity Guaranteed for Certain Periods: where the pension is definitely paid for 5/10/15 or 20 years as chosen, whether the policyholder is alive or not during this period. Post this period, the pension is paid as long as the annuitant is alive. Hence this option will have 4 effective options:

Annuity Guaranteed for 5 years - Example: The policyholder or the nominee will get Rs. 48,300 surely for 5 years, irrespective of the policyholder's survival for 5 years. In case the policyholder survives for 5 years, he/she would continue to get Rs. 48,300 for the rest of his/her lifetime.

Annuity Guaranteed for 10 years - Example: The policyholder or the nominee will get Rs. 47,300 surely for 10 years, irrespective of the policyholder's survival for 10 years. In case the policyholder survives for 10 years, he/she would continue to get Rs. 47,300 for the rest of his/her lifetime.

Annuity Guaranteed for 15 years - Example: The policyholder or the nominee will get Rs. 45,950 surely for 15 years, irrespective of the policyholder's survival for 15 years. In case the policyholder survives for 15 years, he/she would continue to get Rs. 45,950 for the rest of his/her lifetime.

Annuity Guaranteed for 20 years - Example: The policyholder or the nominee will get Rs. 44,400 surely for 20 years, irrespective of the policyholder's survival for 20 years. In case the policyholder survives for 20 years, he/she would continue to get Rs. 44,400 for the rest of his/her lifetime.

Option 3 - Annuity with Return of Purchase Price on Death: pension is paid till the policyholder is alive and the “Purchase Price” or the amount initially invested is paid to the nominee as the death benefit.
Example: The policyholder would receive an annual pension of Rs. 37,550 for the rest of his/her lifetime. Post the policyholder's death, the nominee will receive the Purchase Price of Rs. 5,00,000 and policy are terminated.

Option 4 - Increasing Annuity: pension is paid till the policyholder is alive at an increasing simple rate of 3% per annum.
Example: The policyholder would receive an annual pension of Rs. 39,650 for the first year. The annual payout will increase by Rs. 1,190 (3% of Rs. 39,650) every year for the rest of his/her lifetime.

Option 5 - Joint Life Last Survivor Annuity with 50% for Spouse: pension is paid till the policyholder is alive. On the death of the policyholder, 50% of the pension is payable to a spouse for his/her lifetime. All benefits stop on the death of the spouse also.
Example: The policyholder would receive an annual pension of Rs. 45,200 for the rest of his/her lifetime. After the death of the policyholder, the spouse will be paid Rs. 22,600 (50% of Rs. 45,200) for the rest of his/her life.

Option 6 - Joint Life Last Survivor Annuity with 100% for Spouse: pension is paid till the policyholder is alive. On the death of the life insured, 100% of the pension is payable to the spouse for his/her lifetime. All benefits stop on the death of the spouse also.
Example: The policyholder would receive an annual pension of Rs. 42,150 for the rest of his/her lifetime. After the death of the policyholder, the spouse will be paid Rs. 42,150 (100% of Rs. 42,150) for the rest of his/her life.

Option 7 - Joint Life Last Survivor with Return of Purchase Price: pension is paid till the policyholder is alive. On the death of the policyholder, 100% of the pension is payable to the spouse for his/her lifetime. The purchase price is returned on the death of the policyholder and the spouse.
Example: The policyholder would receive an annual pension of Rs. 37,050 for the rest of his/her lifetime. After the death of the policyholder, the spouse will be paid Rs. 37,050 (100% of Rs. 37,050) for the rest of his/her life. On the death of the spouse, the Purchase Price of Rs. 5,00,000 will also be returned.
 
Once any of the above Options are chosen, it cannot be changed. So please be careful at the very beginning.
Our thoughts on the pension rates – If you are older, the payouts are obviously higher as the company would need to pay you for a lesser period of time.

Now Option 3 can be considered similar to how Fixed Deposits work as the Invested Amount (or Purchase Price) will be returned to the nominee. Depending on your age, you are offered a rate of return between 6.9% to 7.5%. Now, this is lower than the rate of return offered on FDs. However, the rates on FDs are for periods often less than 5 years. There is no guarantee of always getting better rates on FDs. You may find the rate of FDs going lower also over a period of time. In case you buy an Annuity, these uncertainties are taken care of. So it is a good option for those looking for certainty and wanting to lock down the returns which they are expecting for their golden years.

Eligibility conditions and other restrictions in LIC Jeevan Akshay VI plan:


Eligibility Conditions for Jeevan Akshay Plan VI


When will you start getting your pension :   

Depending on the Payment mode selected you will receive your payments are followed:
 
Monthly Mode1 month after purchase of Annuity
Quarterly Mode3 months after purchase of Annuity
Half Yearly Mode6 month after purchase of Annuity
Yearly Mode1 year after purchase of Annuity

To elaborate further with an example: If you take any of the 7 Options for receiving the pension in Monthly mode - you will start receiving the pension from the next month itself. If you choose to receive the pension in Quarterly mode - you will start receiving the pension after 3 months. If you choose to receive the pension in Half Yearly mode - you will start receiving the pension after 6 months. And if If you choose to receive the pension in Yearly mode - you will start receiving the pension after 1 year. This does not depend at the age on which you have taken Jeevan Akshay plan.

Tax Benefits in LIC Jeevan Akshay VI:

The premiums paid by you are exempt from Income tax under Section 80 C. 
The regular pension received by you is however taxable.

What happens if…

You want to surrender the policy – Under most options of this plan, there is no Surrender Value. Which means, there is no option to get back the lump sum amount you have invested. When this plan was launched, there was absolutely no option to surrender. However, some changes have been made and you can get a Surrender Value if you have chosen the "Return of Purchase Price" option in this plan and meet some other conditions. They are as follows:
  • You have shifted permanently to another country of residence
  • You have been diagnosed with some critical illness
Know more about the conditions for Surrendering the LIC Jeevan Akshay Plan - the conditions under which you can do so and the list of critical illnesses.

You want a loan against your policy – Loan facility is not available under this policy.

CLICK HERE TO KNOW YOUR PENSION:
 

PREMIUM CHART:


VIDEO TUTORIAL: